Stocks news · Tuesday 3 November 2026
The latest headlines for this market, then today's other reports from The Zevin Intelligence Journal. Headlines link to the original publishers.
Headlines
- AI trade buckles: Nasdaq 100 enters correction; Kospi and Taiwan -3.6%; US futures slightly lower before vote
Reuters Morning Bid via Investing.com / Saxo · 2026-11-03 - Marvell -12.7%, Lumentum -18.6% on $115bn all-stock merger; Oracle -8.8% on $20bn raise; Europe up on lower oil
Saxo Market Quick Take · 2026-11-03 - Apple falls ~2-2.8% after hours on weaker margin forecast citing memory-chip costs
CNBC / Reuters · 2026-11-02/03
From the Journal today
- Nvidia Tells Its Cloud Partners: Sell Less Computing Power to China
The Zevin Intelligence Journal · Technology · 3 November 2026 - Can a Chatbot Take the News? An EU Court Adviser Says Google's Gemini Might Cross the Line
The Zevin Intelligence Journal · AI · 3 November 2026 - Big Tech's AI Borrowing Spree Heads for Europe's Bond Markets
The Zevin Intelligence Journal · Bonds · 3 November 2026 - Oil Climbs Back Above $106 as Strikes on Qeshm Dim Hopes of Peace
The Zevin Intelligence Journal · Commodities · 3 November 2026

Global bourses retreat on election day
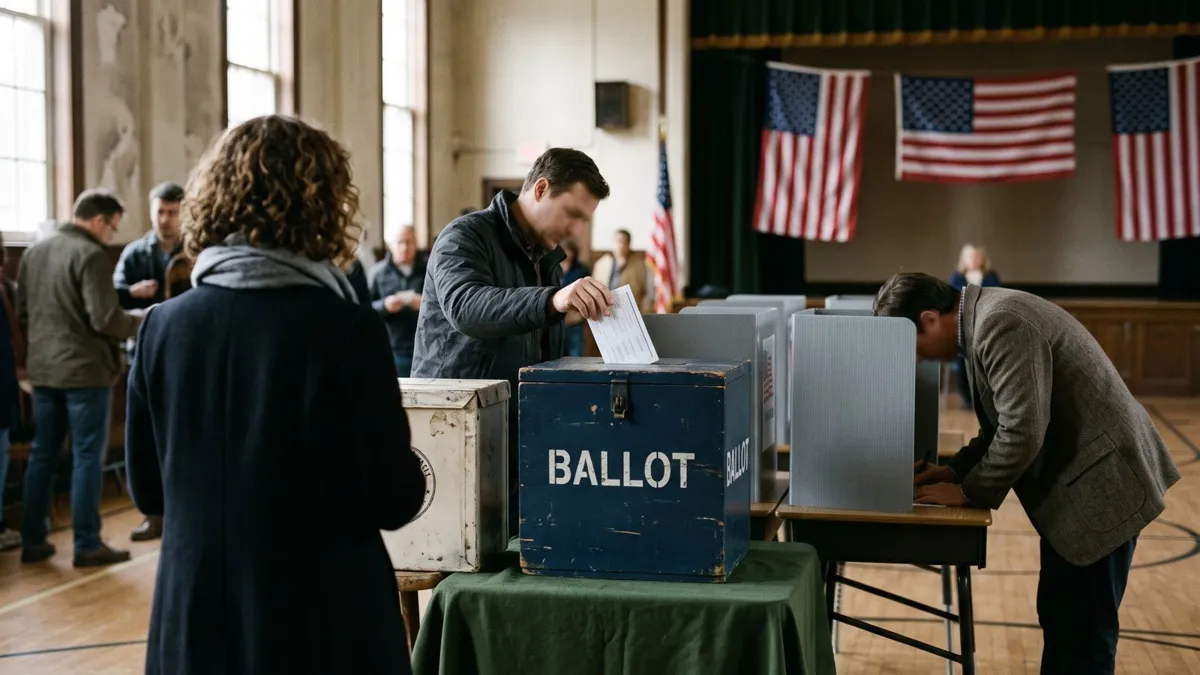
Global stock markets tumbled on Tuesday, Nov 3, under pressure from renewed anxiety over artificial intelligence spending and cautious trading as voters cast ballots in the United States midterm elections.
The pan-European STOXX 600 index fell 0.6% to 645.36 points, while MSCI's gauge of worldwide equities slipped 0.26%. In Asia, South Korea's KOSPI benchmark slid 3.6%, and Taiwan's stock index fell 3.6% in its sharpest single-day retreat since late July. Futures tracking the tech-heavy Nasdaq-100 remained broadly flat, while contracts on the S&P 500 declined 0.14%.
The market pullback matters for everyday investors and retirement savers because a sudden reassessment of artificial intelligence profitability, paired with potential political disruption in Washington, threatens the primary growth engine that has buoyed equity portfolios all year. If corporate earnings can no longer justify elevated spending, broad index funds held by millions of households risk enduring extended volatility.
Midterm voting stokes regulatory scrutiny
Wall Street remained uneasy over lacklustre earnings results and elevated capital spending among dominant technology companies. Betting on the Polymarket platform showed traders pricing in about a 77% chance that the Democratic Party would capture both chambers of the United States Congress.
Such an election outcome could prompt stricter oversight of artificial intelligence and tighter corporate regulation, Alexander Lis, chief investment officer at Social Discovery Ventures, said. In the event of a full Democratic sweep, Lis said he anticipated populist measures targeting artificial intelligence and noted that political narratives opposing data centres would gain momentum.
Analysts at MUFG observed in a note cited by The Business Times that prediction market probabilities had assigned roughly 70% odds to a Democratic sweep, comparing the contest to the 2018 midterms where Democrats captured the House but Republicans retained the Senate. In currency and debt markets, the yield on the 10-year United States Treasury note rose 1.2 basis points to 4.9064%, while Steve Englander, co-head of foreign exchange research at Standard Chartered, said that a surprise Republican victory would probably push yields and the dollar higher.
Apple margin warning deepens tech pressure
Technology sentiment sustained a further blow after Apple forecast lower gross margins for the pivotal holiday quarter on Monday, attributing the compression to rising memory-chip costs. The hardware giant also projected services revenue growth that fell well short of expectations on Wall Street.
Apple shares dropped 2.8% during after-hours trading following the forecast, reported The Business Times. Overnight on Wall Street, the benchmark S&P 500 index slipped 0.5% as tech sector results dragged down investor confidence, even after domestic data demonstrated that United States manufacturing activity expanded in October, The Business Times reported.
Energy and currencies react to geopolitical shifts
Energy markets also experienced volatility as Brent crude futures climbed 1.6% to $106.44 a barrel, after plunging more than 7% on Monday, according to The Business Times. Oil trading reflected erratic signals regarding potential diplomatic resolution between the United States and Iran, as the United States military carried out strikes on Iran's Qeshm Island in the Strait of Hormuz, an American official confirmed to Reuters following an earlier report by The Wall Street Journal.
Those military strikes occurred only hours after United States President Donald Trump said an agreement to conclude the conflict could happen, while Qatari negotiators travelled to Tehran for discussions with Iranian Foreign Minister Abbas Araqchi.
In foreign exchange markets, the United States dollar index dipped to 101.69 after hitting a one-month low on Monday. Against the offshore Chinese yuan, the United States dollar strengthened 0.3% to 6.6645 yuan, The Business Times reported, after the People's Bank of China announced it would elevate the foreign exchange deposit reserve ratio to 6% from 4% beginning Nov 15.
Watch: today's Zevin Newsroom
More from today's Journal
- Nvidia Tells Its Cloud Partners: Sell Less Computing Power to China
- All of today's edition on The Zevin Intelligence Journal
Not investment advice. The content is for information only and is not investment advice or a recommendation to buy or sell securities. Every investment carries risk. Consult a licensed adviser before making any decision.
Analysis first published in The Zevin Intelligence Journal on 3 November 2026. Published on Aizevin Stocks by Rachel, CEO Office.